Startup India recognition can help eligible businesses explore government support and tax-related benefits. However, receiving a DPIIT recognition certificate does not automatically make a startup eligible for every tax deduction or exemption. Different benefits have different eligibility criteria, documentation requirements and approval procedures.
Understanding Startup India tax benefits is essential for founders, CFOs and finance professionals planning their tax position. This guide explains the difference between DPIIT recognition and tax-specific approval, with particular attention to the profit-linked deduction commonly known as Section 80-IAC.
What Is the Difference Between DPIIT Recognition and Tax Benefits?
DPIIT Startup Recognition is granted under the Government of India's Startup India initiative. It establishes that an entity meets the applicable startup recognition criteria.
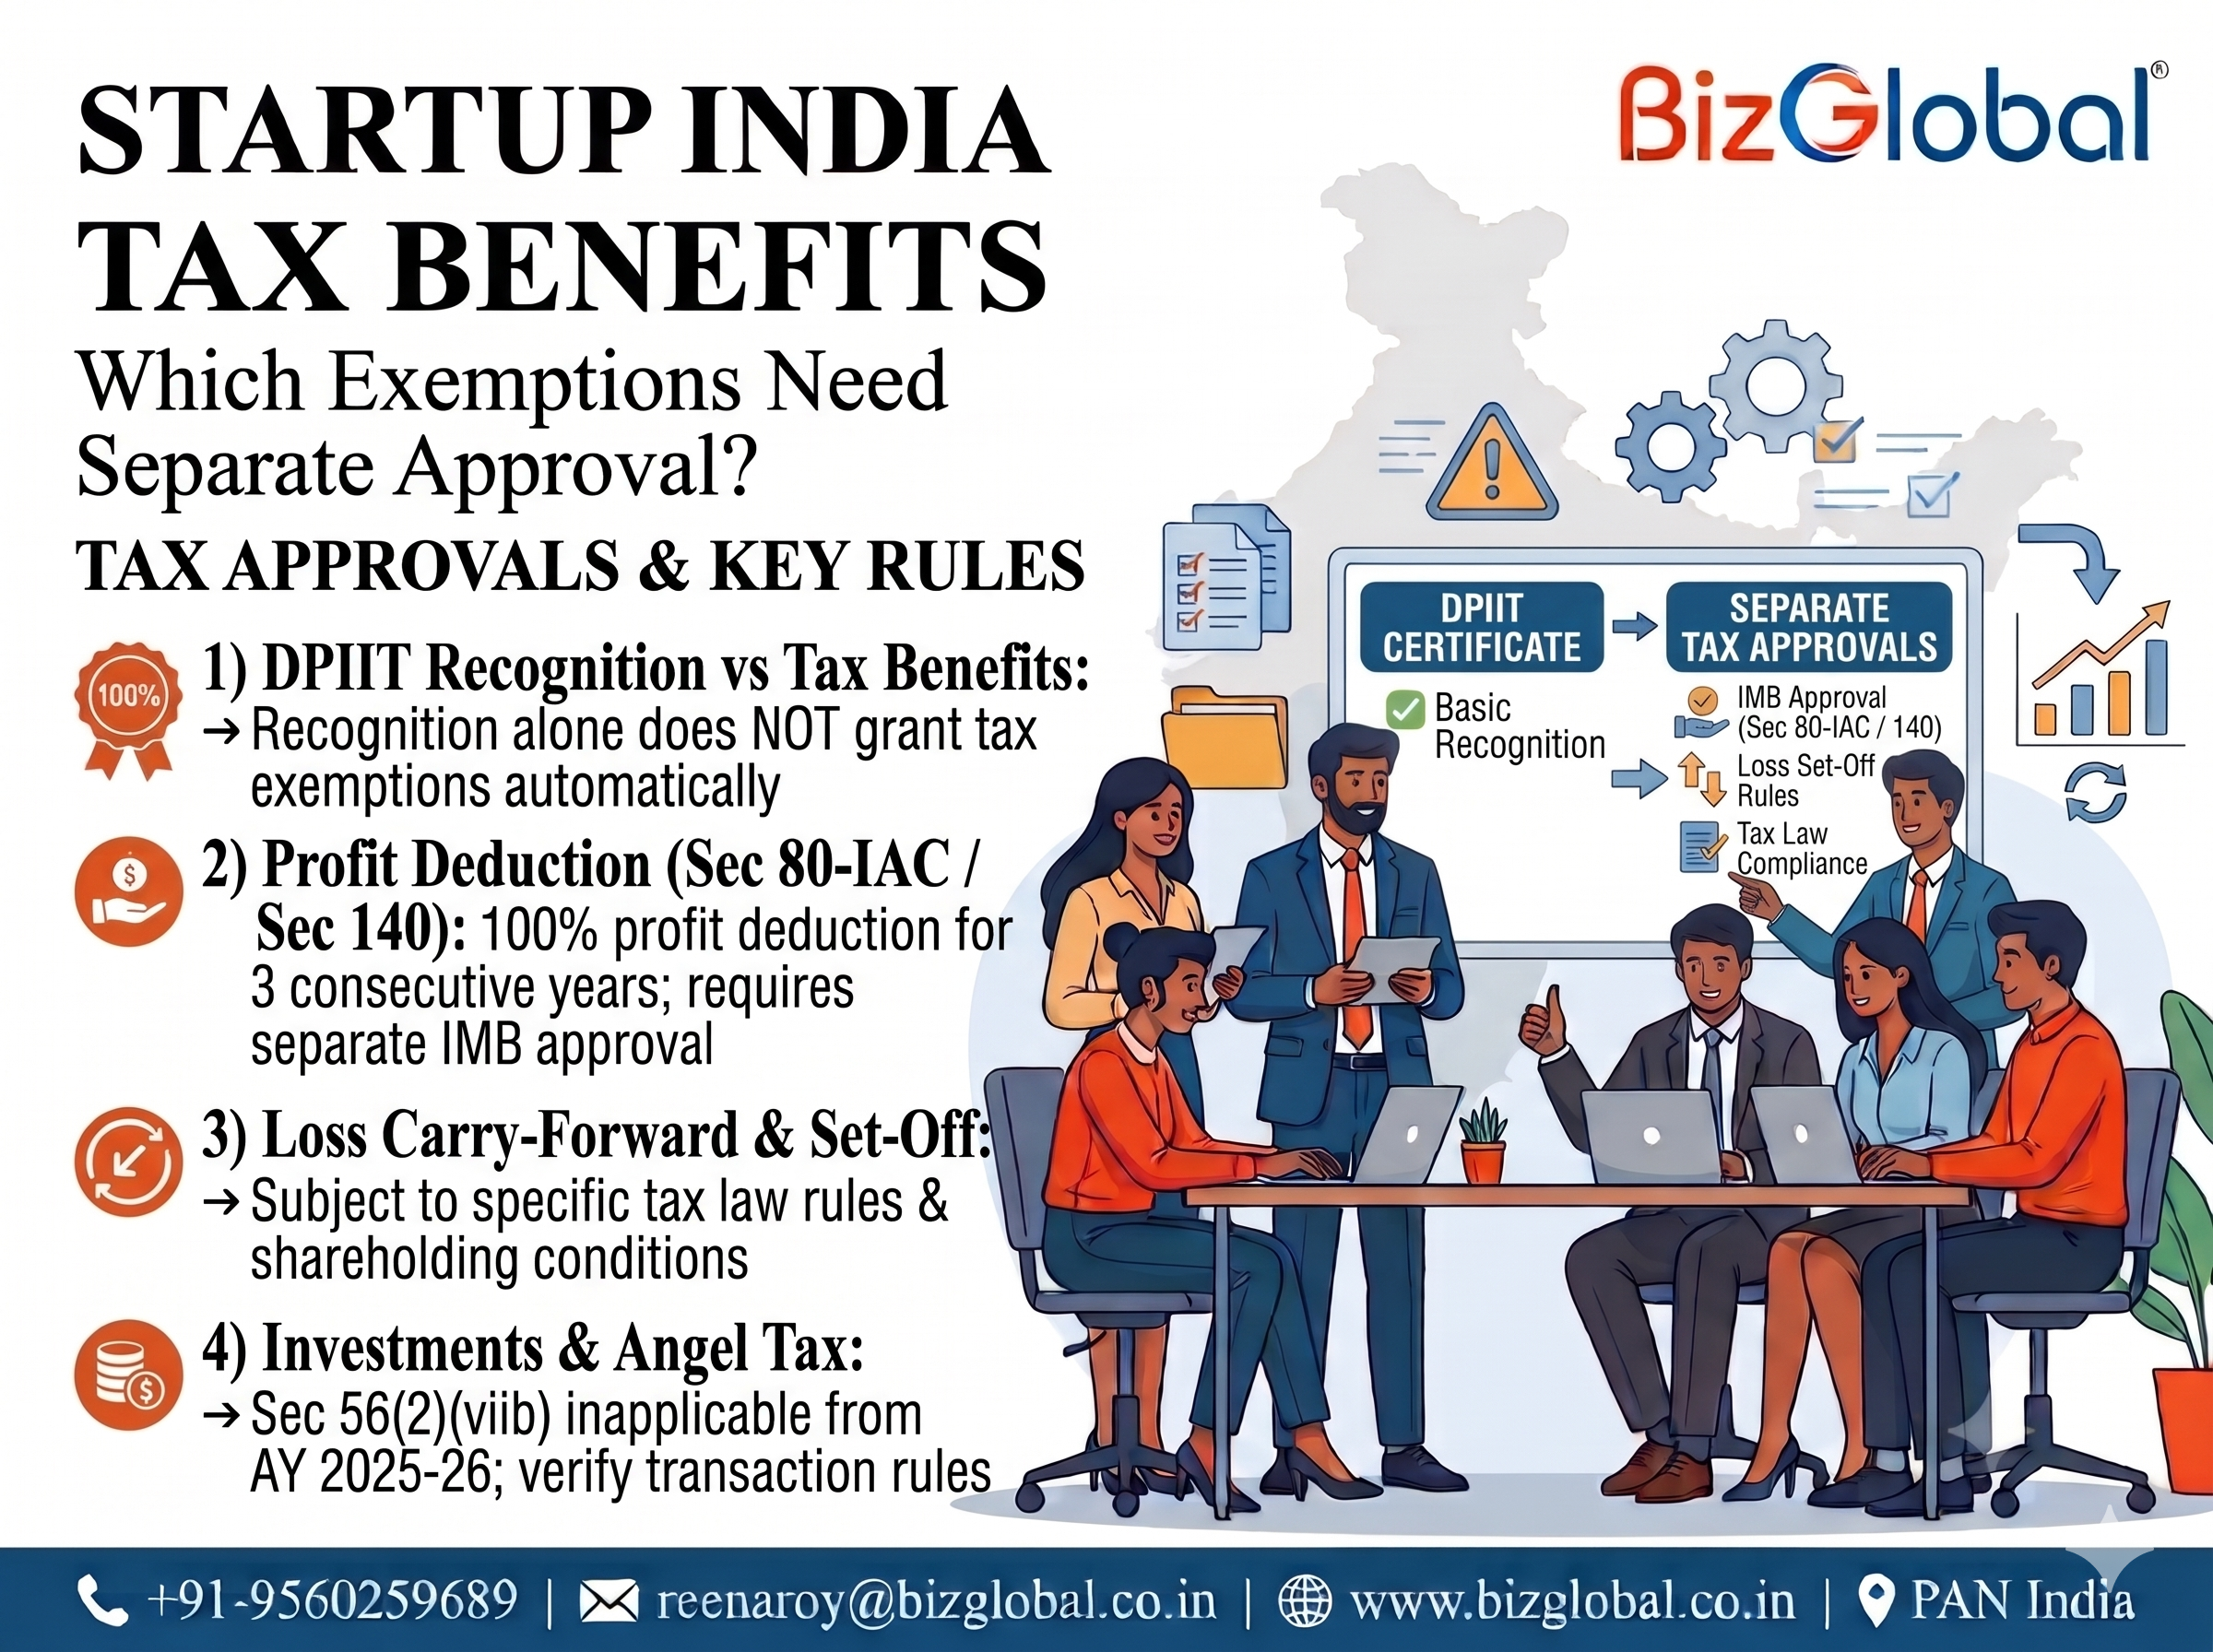
Tax benefits, on the other hand, arise under specific provisions of tax law. A startup may need to satisfy additional conditions, submit a separate application or obtain approval before claiming a particular benefit.
For the broader picture, read our guide to DPIIT Recognition vs Startup India Benefits.
Startup Profit Deduction: Section 80-IAC and the New Tax Law
One of the best-known startup tax benefits is the deduction of eligible business profits for three consecutive years within the prescribed period.
Under Section 80-IAC of the Income-tax Act, 1961, eligible startups could claim a deduction of 100% of profits and gains from the eligible business for three consecutive assessment years out of the first ten years from incorporation.
The Income-tax Act, 2025 came into effect on 1 April 2026. Under the new Act, the corresponding provision is Section 140. Businesses should use the applicable provision based on the relevant tax year and transition rules.
The deduction is subject to conditions. It is not an automatic exemption from every tax liability, nor does it apply simply because a startup has obtained DPIIT recognition.
Does the Profit Deduction Require Separate Approval?
Yes. DPIIT recognition does not automatically establish eligibility for the profit-linked deduction.
Under the established process, an eligible startup must apply for the relevant certificate of eligible business through the prescribed process involving the Inter-Ministerial Board of Certification. The application requires supporting information and may be examined further before approval.
See our detailed guide to Section 80-IAC Startup Tax Exemption: Eligibility and Application.
Are All Startup Tax Benefits Covered by This Deduction?
No. The profit-linked deduction is only one part of the tax framework. Other provisions may affect startups, but their availability depends on the entity, the nature of the transaction and the applicable law.
- Carry-forward and Set-off of Losses
Certain eligible startups may benefit from specific rules concerning the carry-forward and set-off of losses. These provisions have their own conditions, and DPIIT recognition does not remove every requirement under tax law.
- Tax Treatment of Investments
The tax treatment of share issuance, investment receipts and other transactions depends on the applicable provisions. Founders should not assume that recognition automatically exempts all investments from tax scrutiny.
- Other Business Deductions and Incentives
A startup may also explore other deductions or incentives relevant to its activities. These are not universal Startup India benefits; each must be assessed under its own legal framework.
Importantly, the former angel-tax provision under Section 56(2)(viib) was made inapplicable from Assessment Year 2025-26. It should not be presented as a current exemption that startups must newly apply for. Verify the law applicable to the relevant transaction and tax period.
Review the Tax Benefit Applicable to Your Situation
Startup India tax benefits can support financial planning, but only when the business satisfies the relevant requirements. Founders and finance teams should identify the benefit they intend to claim, verify the applicable law and complete any separate approval process before relying on it.
BizGlobal can be approached to discuss startup recognition and related documentation requirements, subject to confirmation of the services offered. For tax eligibility, deduction claims and interpretation of the applicable tax law, consult a qualified tax professional.
Disclaimer: Tax laws and procedures may change. Confirm the applicable provisions, transition rules and eligibility conditions for the relevant tax year before claiming any benefit.